Can You Buy an Apartment in Dubai With a Mortgage? What Applies
Buying an apartment in Dubai with a mortgage is possible for certain non-residents, subject to the lender's approval. Here is how that sits alongside developer payment plans at three published entry prices.
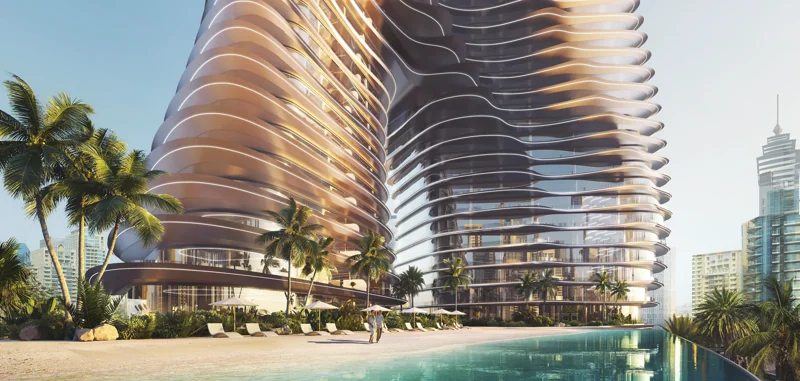
Buying an apartment in Dubai with a mortgage is possible for certain non-residents, always subject to the lender's own approval: there is no guaranteed approval, no fixed interest rate and no standard loan-to-value ratio that applies across every bank. Alongside that route, most off-plan apartments also come with the developer's own instalment plan, which works differently from a bank mortgage.
Two separate financing paths, not one
A developer payment plan is an agreement with the seller: a percentage at reservation, further percentages during construction, and a final percentage at handover, paid directly to the project's escrow account. A mortgage is a separate agreement with a bank, usually used either to fund the handover balance on an off-plan unit or to buy a ready property outright. The two can combine, but your adviser needs to know which one you are planning to use before confirming what a given project requires at each stage.
Three published entry prices and what each payment structure looks like
- Al Habtoor Tower, Business Bay: from AED 2 million, 74 residences across one to three bedroom apartments and penthouses; payment schedule on request.
- Akala, between Downtown Dubai and DIFC: from AED 3.79 million, a 10/50/40 payment plan (10% down, 50% during construction, 40% on handover).
- Address Residences Dubai Hills: price on request, an 80/20 plan with 10% down payment, handover targeted Q1 2029.
| Project | Area | Entry price | Payment plan |
|---|---|---|---|
| Al Habtoor Tower | Business Bay | From AED 2,000,000 | On request |
| Akala | Downtown Dubai / DIFC | From AED 3,790,000 | 10/50/40 |
| Address Residences Dubai Hills | Dubai Hills Estate | On request | 80/20, 10% down |
Where a mortgage typically fits with these plans
For Akala's 10/50/40 structure, a bank mortgage would most commonly be used to cover the 40% due at handover, once the title deed is close to transfer. For Address Residences Dubai Hills' 80/20 plan, the same logic applies to the 20% balance. For Al Habtoor Tower, the payment schedule itself is not published yet, so your adviser confirms the exact structure before any financing conversation makes sense.
What a non-resident mortgage application usually requires
Banks lending to non-residents in the UAE typically look at income documentation, existing liabilities and the property itself as security, with the final decision resting entirely on the lender. No interest rate or approval rate is quoted here, since both vary by bank and by applicant profile. A pre-approval, when offered, is not a guarantee of the final loan amount.
ORVEN PROPERTIES
Talk to an Orven adviser
Leave your number: an adviser calls you back or replies on WhatsApp, in your language. No commitment.
What a mortgage does not change
Regardless of financing, instalments on an off-plan purchase still flow into a Dubai Land Department-controlled escrow account, and Oqood registration still applies from the reservation stage. A mortgage changes who is funding part of your payment, not the registration and escrow mechanics that protect every buyer on an off-plan project.
Why pre-approval timing matters for an off-plan plan
If you intend to use a mortgage for the handover balance on Akala or Address Residences Dubai Hills, getting a sense of your likely pre-approval early, well before the final instalment is due, avoids a last-minute scramble as handover approaches. A pre-approval obtained years ahead of a distant handover date is not binding, since a bank reassesses the application closer to the actual drawdown; it is still useful for planning your own budget around the plan's final percentage.
How the three projects differ beyond financing
Al Habtoor Tower sits within Al Habtoor City, an established mixed-use district with its own hotels and entertainment venues. Akala leans on a wellness-branded concept between two major business districts. Address Residences Dubai Hills carries a hospitality brand alongside direct access to a golf course and shopping mall. These differences shape day-to-day life in the building as much as the financing path does, and are worth weighing alongside the payment mechanics above.
What this costs on top of the purchase price
Dubai Land Department registration is 4% of the purchase price on a completed sale, confirmed at the point of transfer; for an off-plan reservation, Oqood carries its own fixed fee confirmed in the contract. Neither figure is calculated from the entry prices above; ask your adviser for the exact amount once a unit is shortlisted.
Next step
To find out whether a mortgage, a developer payment plan, or a combination of both fits your situation best for Al Habtoor Tower, Akala or Address Residences Dubai Hills, send your target budget on WhatsApp at +971 52 776 1939 or to sales@orvenproperties.com. Our guides on developer payment plans versus mortgages and using a mortgage from your home country's bank go further into the mechanics. For current availability, visit find your home.
FAQ
Can a non-resident get a mortgage to buy an apartment in Dubai? Yes, bank financing is possible for certain non-residents, always subject to the lender's own approval; no rate or approval is guaranteed.
Does a mortgage replace the developer payment plan? Not usually. A mortgage typically covers the balance due at handover or funds a ready property; construction-stage instalments on an off-plan unit still go to the developer's escrow account.
Is Al Habtoor Tower's payment plan published? No, it currently reads "payment schedule on request"; your adviser confirms the current structure.
What is Akala's payment plan? 10% down payment, 50% during construction and 40% on handover, published by the developer Arada.
ORVEN PROPERTIES
Talk to an Orven adviser
Leave your number: an adviser calls you back or replies on WhatsApp, in your language. No commitment.
Frequently asked questions
Can a non-resident get a mortgage to buy an apartment in Dubai?
Yes, bank financing is possible for certain non-residents, always subject to the lender's own approval; no rate or approval is guaranteed.
Does a mortgage replace the developer payment plan?
Not usually. A mortgage typically covers the balance due at handover or funds a ready property; construction-stage instalments on an off-plan unit still go to the developer's escrow account.
Is Al Habtoor Tower's payment plan published?
No, it currently reads "payment schedule on request"; your adviser confirms the current structure.
What is Akala's payment plan?
10% down payment, 50% during construction and 40% on handover, published by the developer Arada.
Continue reading
Guides
Off-Plan Property in Dubai from Emaar: Three Current Releases
Three current Emaar off-plan releases show the range: Address Residences Dubai Hills on an 80/20 plan, Avarra by Palace in Business Bay from AED 2.71 million, and Avelia villas in The Valley from AED 7.25 million.
Read the guide →
Payment plans
Palace Residences Hillside payment plan: how does the 80/20 work?
Palace Residences Hillside in Dubai Hills Estate runs on an 80/20 payment plan with 10% due on booking, starting from AED 1,719,888, with handover targeted for Q2 2029.
Read the guide →
Payment plans
Parkside Views payment plan: what does the 90/10 structure mean?
Parkside Views in Dubai Hills Estate runs on a 90/10 payment plan with a 10% down payment, starting from AED 2,756,888, with handover targeted for Q3 2027.
Read the guide →
Payment plans
VELA Viento Payment Plan: The Full Staged Schedule
VELA Viento's payment plan runs 5% on booking, 20% on SPA signature, then staged payments at months 12, 18, 24 and 30, with 40% due on completion. Pricing starts from AED 17.5 million, handover Q3 2027.
Read the guide →
Payment plans
Is a Mortgage Available for Non-Residents Buying in Batumi?
No Georgian bank, rate or loan-to-value figure is confirmed for non-resident buyers in our Batumi collection. Several developers publish their own instalment plans instead, some running 60 months interest-free.
Read the guide →
Payment plans
Downtown Dubai Payment Plans: Akala and Inaura Compared
Both of Arada's Downtown Dubai wellness towers publish a payment plan, but the split runs opposite directions: Akala front-loads to 10/50/40, while Inaura back-loads to 10/40/50. Akala starts from AED 3.79 million, Inaura from AED 3,599,000.
Read the guide →
Payment plans
Inaura Payment Plan: How the 10/40/50 Schedule Works
Inaura by Arada is priced from AED 3,599,000 on a 10% down payment, 40% during construction, 50% on handover plan. Handover is Q2 2030, across 114 residences in Downtown Dubai.
Read the guide →
Payment plans
Bayz 102 Payment Plan: What the 30/70 Split Means
Bayz 102 by Danube Properties runs on a 30/70 payment plan, priced from AED 2.4 million, with handover targeted for June 2029 across 956 apartments and penthouses in Business Bay.
Read the guide →Explore further
INVESTOR GUIDES